


30 October 2026 | Jakarta, Indonesia
PT Global Digital Niaga Tbk (the “Company”; IDX: BELI), a pioneer and leading omnichannel commerce and lifestyle ecosystem in Indonesia focusing on serving digitally connected retail and institutions consumers, today announced its third quarter earnings results for the year 2026.
KEY HIGHLIGHTS
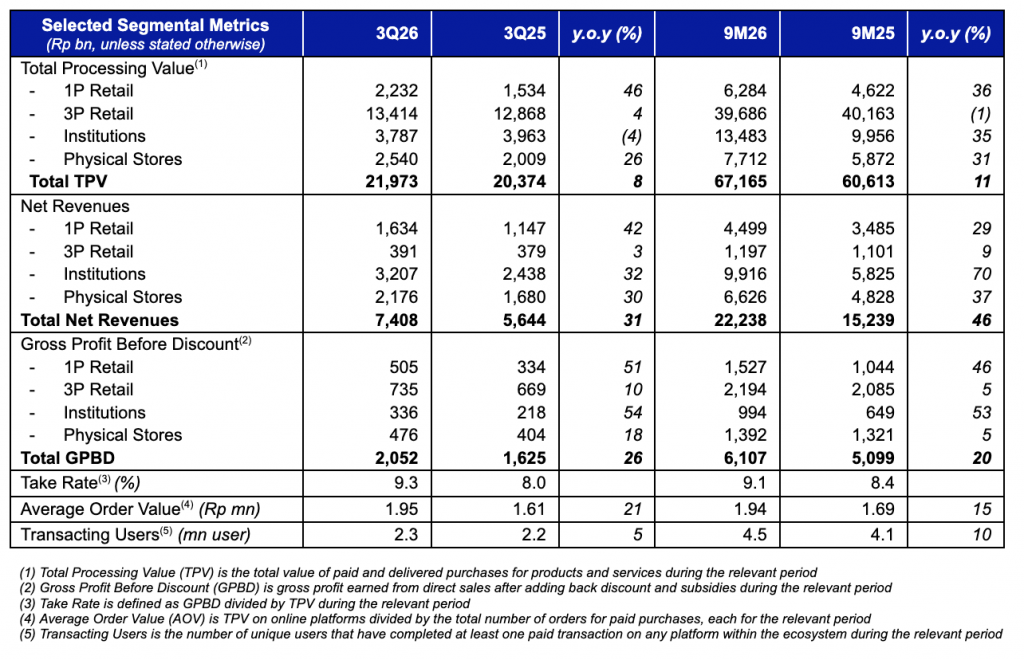
- Consolidated Net Revenues grew by 46% y.o.y from Rp15,239 bn in 9M25 to Rp22,238 bn in 9M26, with solid double-digit growth trajectory across all business segments, especially in the Institutions and Physical Stores segments.
- Take Rate expanded further from 8.4% in 9M25 to 9.1% in 9M26, reaching as high as 9.3% in the 3Q26 period. This was a result of 26% and 20% y.o.y growth in Gross Profit Before Discount (GPBD) during 3Q26 and 9M26, respectively
- Better cost structure reflected by the lower consolidated Operating Expenses as percentage of TPV from 7.2% in 9M25 to 6.4% in 9M26, resulted in an improved performance of consolidated EBITDA as percentage of TPV in the same period by 160bps y.o.y.
- Successfully enhanced supply chain integration and accelerated order fulfillment efficiency for sellers and partners through the fast-growing Fulfillment at Speed (FAS) service.
- Strengthened ecosystem synergies through the launch of the BCA Blibli Tiket Mastercard co-branded credit card, offering a seamless shopping experience, flexible payment options, and multiple exclusive benefits for customers.
- Continued expansion of omnichannel capabilities by adding a total of 31 new stores throughout 3Q26. Hence, as of the end of September 2026, the Company operated a total of 347 consumer electronics stores, 24 home appliance electronics stores, and 1 fashion & sports store. In addition, the Company also managed 60 premium supermarket outlets and 39 home and living experience centers.
MANAGEMENT STATEMENT(S)
Kusumo Martanto – CEO & Co-Founder
“The first nine months of 2026 further demonstrated the resilience of our integrated omnichannel ecosystem and the consistency of our execution against our long-term masterplan. Amid selective consumer spending and intense market competition, we continued to deliver growth while improving profitability and operating efficiency. This progress reflects our focus on high-quality growth, disciplined investment and continuous improvement, rather than growth at any cost.
Across Blibli, tiket.com, Ranch Market and Dekoruma, we continued to strengthen our value proposition through differentiated product and service offerings, deeper partnerships with brand principals, and more seamless integration of our online and offline customer journeys. Balanced contributions from our digital platforms, physical stores, institutional business and partners further enhanced the relevance and resilience of our ecosystem.
We also continued to strengthen the capabilities that support our long-term competitiveness. Selective investments in fulfilment infrastructure, technology and ecosystem integration are improving service reliability, streamlining processes and increasing productivity across our operations. In parallel, we are expanding the responsible use of data analytics and artificial intelligence to improve merchandising, product discovery, customer engagement and decision-making.
As we enter the final quarter of 2026, our priorities remain clear: to strengthen higher-quality revenue growth, further improve operational efficiency and unlock greater value from our integrated ecosystem. We will continue to adapt to changes in consumer behaviour and market conditions, while remain consistent with our long-term strategic direction.
Through disciplined execution, prudent capital allocation and continuous improvement, we are determined to build a more profitable, resilient and differentiated omnichannel business. We remain confident that this approach will create sustainable long-term value for our customers, business partners, shareholders and other stakeholders.”
Ronald Winardi – CFO
“Our financial performance in the first nine months of 2026 reflected the benefits of revenue mix improvement and disciplined cost management. Our top line grew 46% y.o.y, supported by the growth across all business segments. Take rate expansion to 9.1% and a 160bps improvement in EBITDA performance further demonstrated progress in growth quality and operating efficiency. We remain focus on expanding margins, improving operating leverage, and maintaining disciplined capital allocation to accelerate our path toward profitability and build a stronger foundation for sustainable earnings growth and long-term shareholder value.”
KEY OPERATIONAL HIGHLIGHTS
BUSINESS SEGMENTS OVERVIEW
Below is an overview from each of the Company’s business segments during the third quarter of 2026 (3Q26) compared to the third quarter of 2025 (3Q25) period, and the first nine months of 2026 (9M26) compared to the first nine months of 2025 (9M25) period.
1P Retail
1P Retail segment undertakes the Company’s business through its B2C online commerce platform for first party (1P) products and services from various categories.
GPBD for this segment recorded a strong 51% y.o.y growth in 3Q26 to Rp505 bn, and by 46% y.o.y growth in 9M26 to Rp1,527 bn. The improved in GPBD performance was primarily driven by the Company’s continued focus on higher-margin products across key categories, including consumer electronics, home appliances, groceries, and sports & lifestyle. Meanwhile, the home & living business achieved better results through enhanced productivity across its omnichannel operations. Overall, TPV and Net Revenues for this segment grew by 46% and 42% y.o.y in 3Q26, and by 36% and 29% y.o.y in 9M26, respectively.
To support its 1P Retail segment, the Company has a vast network of order fulfillment, logistics and last-mile delivery infrastructure, using hub-and-spoke model, supported by 15 warehouses with a total warehouse area of more than 203,000 square meters, as well as 19 distribution centers (hubs), enabling the Company to offer 2-hour delivery service of more than 480,000 SKUs in more than 40 cities nationwide. Further, the Company also offers Prioritas delivery service, which guarantees customer’s order to be fulfilled and to arrive at the designated address within 30 minutes since the payment is completed.
The warehouse in Marunda, West Java, serves as the main supply chain hub that strengthens the Company’s logistics and fulfillment capabilities, including Fulfillment at Speed (FAS) and Fulfillment by Blibli (FBB) services. Fulfillment business under FAS service has made significant progress by deepening partnerships with several of Indonesia’s leading brand principals, further enhancing supply chain integration and accelerating order fulfillment efficiency. Starting June 2026, the completion of system upgrade under FAS has allowed Ranch Market’s dry goods fulfillment to run through the Marunda warehouse.
As of the end of September 2026, the Company managed 39 home and living experience centers operated by Dekoruma, to expand consumer omnichannel touchpoints in the home & living category for this segment.
3P Retail
3P Retail segment predominantly records the Company’s platform revenue generated from sales of products and services of various categories from third party (3P) sellers through its online commerce and online travel agent (OTA) platforms.
GPBD for this segment recorded a healthy 10% y.o.y growth in 3Q26 to Rp735 bn, and by 5% y.o.y growth in 9M26 to Rp2,194 bn. The improved GPBD performance was mainly driven by higher revenues contribution as well as price optimization and monetization expansion of ancillary revenues in the Company’s OTA business, amidst challenging market backdrops. Overall TPV for this segment declined in 9M26 as the Company shifted some of the 3P category that are deemed strategic to 1P Retail segment in order to have more weight and earn more revenues and higher margin. Meanwhile, Net Revenues for this segment grew by 3% and 9% y.o.y in 3Q26 and 9M26, respectively.
As of the end of September 2026, the Company’s OTA platform, tiket.com, offered a variety of products and services, including flight tickets from 168 domestic and international airlines serving more than 240 countries, regions, and territories, providing more than 3.6 million accommodation options, including more than 2.2 million options of alternative accommodations, and offering approximately 118,000 activities and tourist destinations as well as more than 4,600 events worldwide.
Institutions
Institutions segment includes the Company’s commerce business through its online platforms for 1P and 3P products and services serving institutional clients across Indonesia.
GPBD for this segment recorded a strong 54% y.o.y growth in 3Q26 to Rp336 bn, and by 53% y.o.y growth in 9M26 to Rp994 bn. The improved GPBD performance was mainly attributable to the success in regional expansion in the consumer electronics (smartphone) and home appliance electronics categories, which resulted in a higher sales volume to institution clients. During the period, this segment also managed to significantly improve the quality of its clients, reflected in higher spending per institutional client by 63% y.o.y to Rp145.1 mn. Overall, Net Revenues for this segment grew by 32% and 70% y.o.y in 3Q26 and 9M26, respectively.
Throughout the period, the Company’s Institutions segment served approximately 93,000 institutional clients, with a continuous growth of monetization rate from 59% in 9M25 to 74% in 9M26, reflecting increasing trust by institutional clients on the services provided by the Company.
Physical Stores
Physical Stores segment records the Company’s business in physical consumer electronics stores (focusing on smartphones, tablets and related products), home appliance electronics stores, and fashion & sports stores, collaborating with leading global brand principals, as well as premium grocery supermarket chain operated by 70.6%-owned subsidiary, PT Supra Boga Lestari Tbk (“Ranch Market”; IDX: RANC).
GPBD for this segment recorded an 18% growth in 3Q26 to Rp476 bn, and by 5% y.o.y growth in 9M26 to Rp1,392 bn. The improved GPBD performance was mainly driven by the higher smartphone sales volume on the back of new products launch and the continued expansion of the Company’s consumer electronics and home appliances electronics stores. In addition, the Company’s supermarket outlets also recorded better margin during the period with improved Same-Store Sales Growth (SSSG) as well as better overall operational efficiency and shrinkage management. Overall, TPV and Net Revenues for this segment grew by 26% and 30% y.o.y in 3Q26, and by 31% and 37% y.o.y in 9M26, respectively.
With the addition of 31 new stores throughout the period, the Company operated a total of 347 consumer electronics stores, which consisted of 160 monobrand stores and 187 multibrand stores, as well as 24 home appliance electronics stores and 1 fashion & sports store as of the end of September 2026. In addition, the Company also managed 60 premium supermarket outlets operated by Ranch Market.
CONSOLIDATED FINANCIAL PERFORMANCES
MANAGEMENT DISCUSSION & ANALYSIS
Below are brief descriptions of the Company’s consolidated financial performance during the third quarter of 2026 (3Q26) compared to the third quarter of 2025 (3Q25) period, and the first nine months of 2026 (9M26) compared to the first nine months of 2025 (9M25) period.
Revenue & Profitability
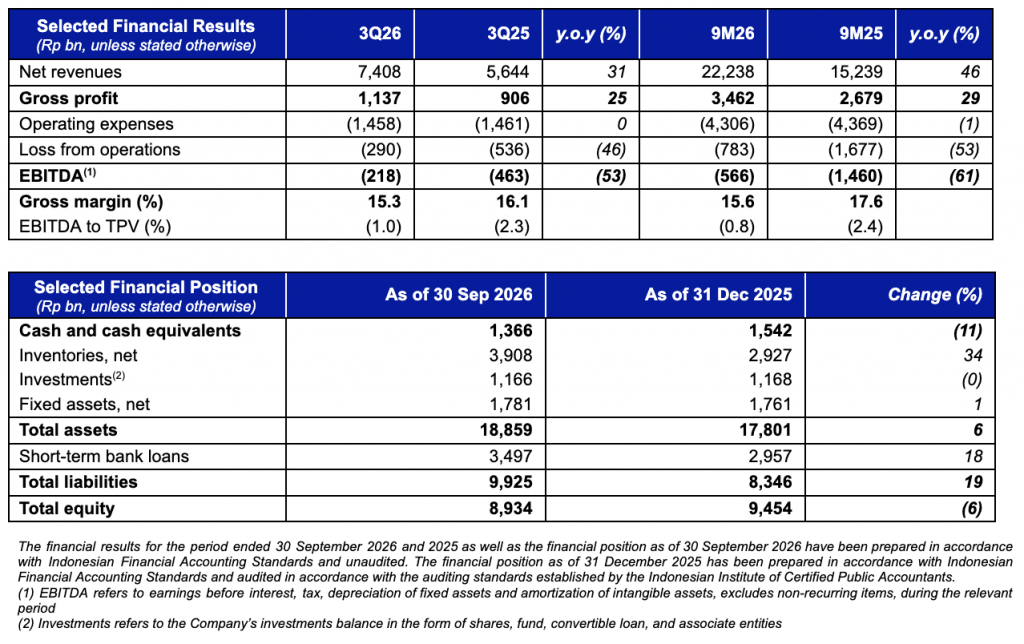
Consolidated Net Revenues recorded a solid 31% y.o.y growth from Rp5,644 bn in 3Q25 to Rp7,408 bn in 3Q26, and by 46% y.o.y growth from Rp15,239 bn in 9M25 to Rp22,238 bn in 9M26. This was largely driven by the improved contribution across all business segments, especially in the 1P Retail segment, which benefited from higher sales of smartphones and sports products, improved contribution from the OTA and institutional businesses, as well as an expanding physical stores network to deepen the Company’s omnichannel presence and penetration. The changes in product mix resulted in a normalized overall consolidated Gross Margin to 15.6% in 9M26.
Throughout the period, the Company managed to further improve its operational excellence which resulted in a better cost structure, reflected in lower consolidated Operating Expenses as percentage of TPV from 7.2% in 9M25 to 6.4% in 9M26, mainly supported by the more efficient consolidated advertising and marketing as well as general and administrative expenses as percentage of TPV. Overall, the Company continued to improve its performance, reflected by the improved consolidated EBITDA as percentage of TPV from -2.4% in 9M25 to -0.8% in 9M26, an improvement of 160bps y.o.y.
Cash Flows
Net cash used in operating activities was recorded at Rp721 bn in 9M26, mainly due to investment in working capital to support accelerating Net Revenues growth. Net cash used in investing activities was recorded at Rp277 bn in 9M26, mainly used for physical stores expansion. Meanwhile, net cash provided by financing activities was recorded at Rp821 bn in 9M26. Therefore, the Company’s consolidated Cash and Cash Equivalents position was recorded at Rp1,366 bn as of 30 September 2026 compared to Rp1,542 bn as of 31 December 2025.
Performance Guidance
The Company reiterates its target to achieve a 15–20% increase in consolidated Net Revenues in 2026. This target is supported by key strategic priorities to be executed for the remainder of the year, with a continued focus on margin improvement and a more efficient cost structure.
ENVIRONMENTAL, SOCIAL & GOVERNANCE (ESG)
The Company remains committed to delivering sustainable growth and long-term value creation. Through Blibli Tiket Action, the Company advances its Environmental, Social, and Governance (ESG) agenda while engaging stakeholders to create lasting positive impact. The following highlights reflect the Company’s ESG progress during 9M26:
Environmental Focus
The Company continued to reinforce its environmental commitments through responsible resource, waste, and emissions management:
- Sustainable Resource Management: approximately 88% of packaging consisted of FSC-certified cardboard and paper-based materials, reinforcing the adoption of eco-friendly packaging across the ecosystem.
- Responsible Waste Management: strengthened office waste-sorting practices across offices within the ecosystem and collected approximately 890 units of e-waste through Gadget for Good program, located at multiple Blibli stores across Greater Jakarta.
- Emissions Reduction: expanded customer participation through always-on sustainability features:
- Misi Tanam Pohon: over 200 trees are scheduled to be planted in November 2026, funded by customer donations of Rp1,000 per transaction.
- Green Delivery: completed more than 38,000 low-emission deliveries by prioritizing electric vehicle (EV) delivery options.
Social Impact
The Company continued to invest in its people and communities through initiatives that foster capability, collaboration, and responsible digital behavior:
- Winning Culture: fostered the four Winning Principles through the Winning Ambassadors Program, with the newly appointed ambassadors leading the initiative for the 2026–2027 period.
- Employee Development: strengthened employee capabilities through Blibli Talks, a regular knowledge-sharing forum, and CollaborAction, an internal sustainability education and engagement program.
- Stakeholder Engagement: delivered the 5th edition of Langkah Membumi through a Networking Dinner and Goes to Campus program, followed by a four-day Langkah Membumi Market at Grand Indonesia on 8–11 October 2026.
- Digital Literacy & Customer Protection: continued the JEDA 10 Detik campaign to promote digital literacy, critical thinking, and informed customer decision-making.
Governance Excellence
The Company strengthened its digital trust and sustainability leadership through internationally recognized standards and industry awards:
- Certifications: maintained ISO 27001:2022 for Information Security Management, ISO 27701:2019 for Privacy Information Management, and PCI DSS 4.0.1 Merchant Level 1 certification.
- Sustainability Awards: recognized with the Change the World Award 2026, Indonesia Sustainability Award 2026, and Indonesia Best Corporate Sustainability Initiatives 2026 by SWA Media Group for Langkah Membumi in the Cause Promotion category.
BUSINESS PROSPECTS
The Company expects the operating environment to remain competitive through the remainder of 2026, with consumer spending likely to recover gradually and unevenly amid continuing macroeconomic uncertainty. Against this backdrop, strategic priority remains unchanged: to deliver sustainable, high-quality growth while continuing to improve profitability and operational efficiency.
The Company will focus on strengthening the quality of its revenue mix through selective category expansion, deeper partnerships with brand principals and institutional clients, as well as the continued scaling of its integrated omnichannel ecosystem. Further, it will also enhance fulfilment capabilities and the use of technology, data analytics and artificial intelligence to improve customer experience, decision-making and productivity.
Seasonal events, including National Online Shopping Day (Hari Belanja Online Nasional/Harbolnas) and the year-end holiday period, are expected to present additional opportunities, particularly in consumer electronics, travel and lifestyle categories. The Company will pursue these opportunities through disciplined commercial execution and close collaboration with brand and business partners, while maintaining prudent cost management and capital allocation.
The integration of digital platforms, physical stores, trusted consumer brands, fulfilment infrastructure and technology provides a differentiated foundation for delivering more seamless customer experiences, strengthening the Company’s proposition to sellers and brand partners, and generating greater operating leverage over time. With clear long-term strategy, expanding omnichannel capabilities and continued focus on execution, the Company remains committed to advancing towards sustainable profitability and creating enduring value for all stakeholders.
-END-